How to Identify Damage to Your Roof
After a hurricane, identifying roof damage promptly is critical to preventing further structural issues or costly repairs. High winds, flying debris, and heavy rainfall can all contribute to hidden or visible damage. Assessing the condition of your roof ensures safety and helps you take immediate action.
Initial Safety Precautions
Before inspecting your roof, prioritize safety:
– Wait for the storm to fully pass: Avoid assessing damage during extreme weather conditions.
– Check for hazards: Be mindful of downed power lines, broken glass, or unstable structures around your property.
– Use protective gear: Wear sturdy shoes with good grip and gloves if you need to handle debris.
– Avoid climbing onto the roof immediately: Use binoculars or view from the ground first. Roofs may be unstable after severe weather.
Signs of Roof Damage
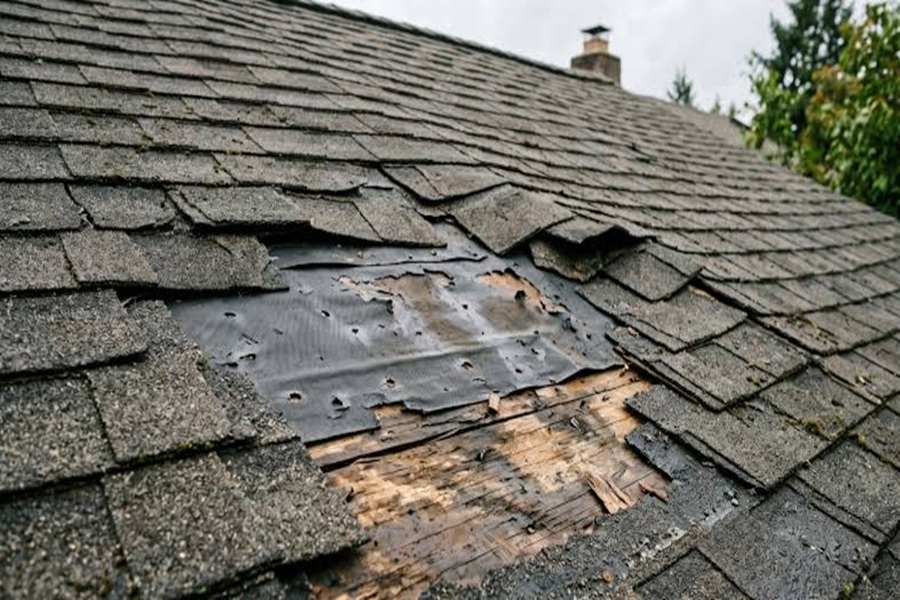
- Look for shingles that are cracked, curled, broken, or entirely missing. Asphalt shingles may also appear granule-less due to wind abrasion.
- Pay attention to bare spots on the roof where shingles used to be attached.
- Check ceilings and walls for water stains or discoloration that might indicate leaks caused by compromised roofing materials.
- Look in corners and attic spaces where water pooling often occurs.
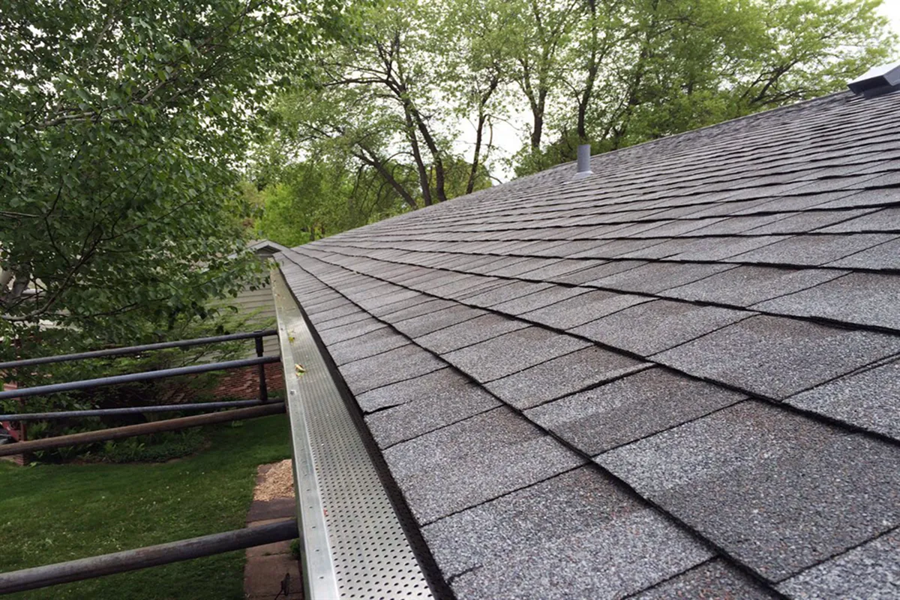
- Inspect gutters for dents, sagging sections, or blockages caused by debris.
- Check if roof runoff is being properly redirected; damaged gutters can worsen water damage.
- Look out for sagging areas on your roof that could suggest structural weakening.
- Examine supporting beams in attics for cracks or bending under pressure.
- Large branches or other debris may leave holes in the roofing material.
- Note any scratches, punctures, or torn flashing around chimneys and vents.
Tools You May Need
Tool | Purpose |
Binoculars | Allows detailed inspection from a distance |
Flashlight | Helps identify damage in dark attic spaces |
Camera/Smartphone | Document visible damages (photos/videos) |
Should You Call a Professional?
While minor damages might be visible from ground level, more serious concerns—like structural instability—require professional evaluation. Contact a licensed roofing contractor if you notice any of these signs:
– Large portions of missing shingles/debris penetration holes
– Severe sagging in sections of your roof
– Persistent leaks despite temporary fixes
Importance of Documentation
Accurate documentation is essential when dealing with insurance claims (covered later in this article). Follow these steps:
1. Take clear photos/videos from multiple angles showing all observed damages. 2. Record dates of inspection and details about potential causes (e.g., fallen trees). 3. Keep damaged items like broken shingles as evidence when safe to do so.
Early identification minimizes repair costs while ensuring the safety and integrity of your home after a hurricane event.
Take Action on Storm Damage
1. Prioritize Safety First
- Inspect surroundings: Before approaching your home or roof, check for hazards such as downed power lines, fallen trees, or debris that could cause injury.
- Avoid unstable areas: If parts of the roof appear to be sagging or if structural integrity is compromised, stay away and contact professionals immediately.
- Turn off utilities if necessary: If you suspect electrical or gas line damage, shut off utilities and wait for expert assessment.
2. Perform a Preliminary Roof Inspection
While it’s best to leave detailed assessments to professionals, a basic visual inspection can help you understand the urgency of repairs: – Look for missing shingles, exposed underlayment, or visible holes in the roof. – Check gutters and downspouts for accumulated granules from shingles, which may indicate significant wear. – Assess flashing around vents, chimneys, or skylights for signs of damage or gaps.
3. Document All Damage
Accurate documentation is essential for insurance claims and repair planning: – Take photographs and videos of all visible damage from multiple angles. This includes interior water stains caused by potential leaks. – Create a checklist of damaged areas such as shingles, soffits, fascia boards, gutters, and attic spaces.
Key Area | Signs of Damage |
Shingles | Missing pieces; cracks; curling edges |
Flashing | Gaps; bent sections; missing components |
Gutters/Downspouts | Detachments; dents; granule buildup |
Interior Ceilings | Stains; discoloration; sagging drywall |
4. Prevent Further Damage
Mitigating additional harm while waiting for permanent repairs is crucial: – Tarp your roof: Cover damaged areas with waterproof tarps to prevent water infiltration during subsequent rains. – Remove heavy debris like tree branches carefully without causing further structural strain. – Clear out gutters clogged by storm debris to avoid water pooling near your home’s foundation.
5. Hire Professional Help
Some tasks require expertise beyond DIY efforts: – Reach out to licensed roofing contractors for an in-depth inspection and detailed repair plan. – Avoid storm-chasing contractors who may appear after major weather events offering quick fixes at unusually low prices. Verify credentials through references or trusted local directories.
6. Communicate with Insurance Providers
If insurance covers your damages (elaborated separately), keep open communication with your insurer regarding timelines for inspections and coverage approvals.
By taking these steps promptly after discovering storm-related roof issues, you can limit further harm while ensuring a smoother restoration process ahead. Always prioritize professional guidance when dealing with extensive structural concerns to protect yourself and your home effectively.
Insurance Claims
Step 1: Assess the Damage
Before contacting your insurance company, conduct a thorough assessment of the damage. Be sure to document everything carefully.
- Take Photos and Videos: Capture clear, detailed images of all visible roof damage, including missing shingles, leaks, structural issues, and debris impact.
- Look for Interior Damage: Check ceilings and walls for water stains or signs of leaking that might be related to roof damage.
- Create an Inventory: List any personal property affected by water intrusion caused by roof damage.
Step 2: Review Your Insurance Policy
- Coverage Details: Verify what types of storm-related damages are covered under your policy.
- Deductibles: Understand how much you’ll need to pay out-of-pocket before coverage kicks in.
- Exclusions: Be aware of any exclusions in the policy that could affect your claim (e.g., wear-and-tear or maintenance issues).
Step 3: Notify Your Insurance Provider
Reach out to your insurance company promptly after assessing the damage.
- Contact their claims department and provide preliminary information about the extent and nature of the roof damage.
- Ask whether they require immediate mitigation steps (e.g., tarping over exposed areas) while waiting for adjusters.
Tip: Many policies have a limited timeframe for filing claims after an incident, so don’t delay making that initial contact.
Step 4: Work with an Adjuster
Once you file a claim, your insurance company will assign an adjuster to evaluate the extent of damages.
- Be present during their inspection to answer questions or provide additional documentation.
- Share photos/videos and your inventory list with them as supporting evidence.
Pro Tip: Consider consulting a licensed roofing contractor who can independently assess storm-related damage. Their expertise can help confirm whether repairs suggested by the adjuster are sufficient.
Step 5: Gather Repair Estimates
- Material costs (e.g., shingles, underlayment)
- Labor charges
- Miscellaneous expenses like permits or waste removal
Step 6: Mitigate Further Damage
- Cover holes or leaks with waterproof tarps.
- Remove loose debris from rooftops (only if it’s safe) or hire professionals if necessary.
Document these actions as insurers may reimburse reasonable emergency expenses incurred during this period.
Common Challenges During Claims Process
Challenge | Solution |
Claim Denial | Request clarification; appeal with additional evidence where possible. |
Delayed Adjuster Visits | Follow up consistently; escalate concerns if delays persist longer than reasonable timelines. |
Low Settlement Offers | Negotiate by providing thorough contractor estimates & proof-of-loss documentation. |
Remember that persistence is key when dealing with insurance companies. Stay organized throughout this process by keeping all receipts related repair costs filed neatly alongside communication records between yourself & insurer
Insurance Claims
Navigating the insurance claims process after hurricane roof damage can feel overwhelming, but taking the right steps ensures you’re fairly compensated for repairs. Here’s a step-by-step guide to help you handle insurance claims efficiently and effectively.
1. Document the Damage Thoroughly
Proper documentation is critical for an accurate and successful claim. Start as soon as it’s safe to do so.
- Take photos and videos: Capture clear, detailed images of all damaged areas from multiple angles, including missing shingles, leaks, dents, or structural issues.
- Document secondary damage: Note any additional damage inside your home caused by roof issues, such as water stains on ceilings or damaged furniture.
- Keep receipts: Save receipts for temporary repairs (e.g., tarps) or emergency expenses like hotel stays if your home is uninhabitable.
2. Notify Your Insurance Provider Promptly
Contact your insurance company as soon as you are able. Many policies have time limits within which a claim must be filed.
- Provide preliminary information: Have your policy number and details about the storm event ready.
- Discuss temporary repairs: Confirm what emergency repairs (like tarping) are covered under your policy before you proceed with any work.
3. Review Your Policy Coverage
Before filing a claim, understand what type of coverage you have for roof damage due to hurricanes.
- Dwelling coverage: This typically includes structural damages to your roof and other parts of the home caused by wind or hail.
- Exclusions or limitations: Be aware of exclusions like wear-and-tear or pre-existing issues that might not be covered.
- Deductible amount: Check how much you’ll need to pay out-of-pocket before insurance kicks in.
4. Schedule an Inspection with an Adjuster
Once you’ve reported the claim, your insurer will likely send a claims adjuster to assess the damage.
- Be present during the inspection: This allows you to point out specific damages and ensure nothing is overlooked.
- Provide evidence: Share all photos, videos, and documentation you’ve gathered with the adjuster for reference.
5. Get Estimates from Roofing Contractors
- Contact licensed roofing contractors for professional repair estimates.
- Compare estimates to ensure fair pricing. Many insurers require multiple quotes before approving major repair work.
Use caution when hiring contractors; avoid those who pressure you into signing contracts immediately or demand upfront payments without providing clear terms in writing.
6. Follow Up on Your Claim
- Keep regular communication with your insurance provider to check on the progress of your claim.
- Respond promptly if more information is requested by either the adjuster or insurer.
Process Step | Key Action Items |
Document Damage | Take photos/videos; save receipts |
Contact Insurer | Notify provider; confirm protocol |
Understand Coverage | Review policy details |
Meet Adjuster | Attend inspection; provide evidence |
Gather Repair Estimates | Obtain quotes; vet contractors carefully |
7. Use Insurance Proceeds Wisely
- Prioritize necessary repairs to restore safety and functionality first.
- Keep records of how funds are spent in case they are needed later for additional claims-related purposes.
Navigating this process takes patience but ensures that financial losses are minimized while restoring safety and security to your home after hurricane-related roof damage has occurred.
Insurance Claims
Dealing with insurance claims after your roof has been damaged by a hurricane can feel overwhelming, but a structured approach can make the process more manageable. Understanding how to navigate insurance claims is essential to ensure you receive the compensation needed to repair or replace your roof effectively. Here is a detailed guide on managing this process.
Begin Documentation Immediately
- Photograph the Damage: Take clear photos of all visible roof damage from multiple angles. Include close-up shots of missing shingles, cracks, holes, or any debris that may have caused additional harm.
- Document Interior Damage: If water has leaked into your home due to the roof damage, photograph interior issues such as water stains on ceilings, damaged walls, or ruined belongings.
- List Damaged Items: Create a written inventory of any property affected by the storm (e.g., furniture, electronics) and assign approximate values to them.
Notify Your Insurance Company
- Have Your Policy Information Ready: Provide policy numbers and other necessary information when speaking with an insurance representative.
- Describe the Damage Clearly: Use specific terms when explaining the extent of the damage; avoid generalizations such as “a lot” or “extensive.” For instance, mention how many shingles are missing or whether structural components are affected.
- Request Guidance for Next Steps: Ask if they need additional documentation or if they recommend temporary repairs while waiting for an adjuster.
Work with an Insurance Adjuster
- Be Present During Inspection: Walk through the property with the adjuster and point out areas of concern they might overlook (e.g., less visible spots like gutters).
- Share Your Documentation: Provide photos and written records you’ve compiled so far.
- Take Notes During Meetings: Record important observations made by both you and the adjuster for reference throughout the claims process.
Checklist for Meeting with an Adjuster |
Be available during their scheduled visit |
Present photos/videos documenting damage |
Discuss all damaged areas (interior/exterior) |
Understand Your Policy Coverage
- Check if there’s coverage for hurricane-related wind or water damage.
- Look into exclusions; for example, some policies may not cover older roofs past a certain age.
- Determine if there’s separate deductible criteria related to natural disasters.
If you’re unsure about certain clauses in your policy, consult directly with your agent or hire an independent public adjuster who can advocate on your behalf.
Consider Professional Assistance
- Some contractors work directly with insurance companies to simplify processes for homeowners.
- Avoid agreeing to services before verifying contractor credentials; always check references and reviews first.
By remaining organized throughout this process and maintaining open communication with both insurers and roofing professionals, you’ll be better positioned to restore your home efficiently following hurricane roof damage.
Insurance Claims
1. Document the Damage Thoroughly
Before contacting your insurance company, gather detailed evidence of the damage. Proper documentation helps establish a clear case for your claim.
- Take Photos and Videos: Capture images of all visible roof damage, such as missing shingles, dents, holes, or water stains inside your home. Include wide-angle shots of the roof and close-ups of specific issues.
- Record Dates and Details: Write down when the hurricane occurred, as well as any immediate repairs or temporary fixes you made to prevent further damage.
- Keep Damaged Items: If debris fell into your yard or home (e.g., broken shingles), save these items as supporting evidence.
2. Review Your Insurance Policy
Understanding what your policy covers is crucial during this stage.
- Policy Limits and Deductibles: Check if your policy covers wind, rain, or hurricane-related damages specifically. Be aware of any deductibles that apply to hurricane claims.
- Exclusions: Some policies may exclude certain types of storm damage; review these details carefully.
- Additional Coverage Options: Look for endorsements like code upgrade coverage in case repairs need to meet new building codes.
3. Contact Your Insurance Provider
Notify your insurer about the damage as soon as possible. Most companies have specific timelines for filing claims after severe weather events.
When you call: – Provide a description of the damage using the evidence you’ve collected. – Request an adjuster visit to assess the extent of destruction. – Ask about timelines for claim processing and what additional documents might be required.
4. Prepare for an Adjuster’s Inspection
When an adjuster visits your property: – Be present if possible to answer any questions about how and when the damage occurred. – Share all photos, videos, receipts for temporary repairs, and other supporting documents. – Point out less obvious issues (e.g., leaks inside attics) they might miss during their inspection.
5. Keep Track of Expenses
While waiting on claim approval: – Maintain records of temporary repair costs (e.g., tarping) and any invoices from professionals who assisted with immediate fixes. – Save receipts for lodging or meals if you had to leave your home due to unsafe conditions caused by roof damage.
Expense Type | Examples | Documentation Needed |
Temporary Repairs | Tarp materials, labor costs | Receipts or invoices |
Living Expenses | Hotel stays, meals | Receipts with dates/amounts |
Permanent Repairs/Replacement | Roofing contractor fees | Signed contracts & detailed invoices |
6. Follow Up Regularly
Communicate consistently with your insurer throughout the process: – Confirm they’ve received all necessary paperwork. – Stay informed about their progress in evaluating your claim.
If delays occur or disagreements arise regarding coverage amounts: – Consider hiring a public adjuster who works independently from insurance companies to negotiate on your behalf.
Understanding how to handle insurance claims effectively ensures that you’ll receive appropriate compensation with minimal disruption to repair efforts. By being thorough in gathering evidence and staying proactive during communication with insurers, you can navigate this critical step confidently after experiencing hurricane-related roof damage.
Insurance Claims
Filing an insurance claim after hurricane roof damage can feel daunting, but it’s a crucial step to ensure you receive the financial support needed to repair or replace your roof. Approaching the process methodically and being well-prepared can make a significant difference in the outcome of your claim. Here’s a guide to navigating insurance claims effectively.
Understand Your Policy
- Coverage Specifics: Check if your policy covers wind and water damage caused by hurricanes. Some policies may exclude certain natural disasters or limit coverage for specific types of damage.
- Deductibles: Determine how much you’ll need to pay out-of-pocket before coverage kicks in.
- Documentation Requirements: Some insurers require detailed evidence of damage, so familiarize yourself with what is needed.
Document the Damage
- Photographs and Videos: Capture clear images or videos of all visible roof damage, including missing shingles, cracks, leaks, or structural issues.
- Interior Evidence: If water has entered your home due to roof damage, document interior signs as well (e.g., ceiling stains or peeling paint).
- Detailed Notes: Write down specifics about the storm itself—date, time, and severity—as well as observations about when you first noticed issues.
Keeping these records organized will strengthen your claim.
Temporary Repairs
- Cover exposed sections with tarps or heavy-duty plastic sheeting.
- Patch small leaks using roofing tape or sealants.
Be sure to save all receipts for materials used in these temporary repairs. Most insurers will reimburse reasonable costs for such efforts.
Notify Your Insurer Promptly
Reach out to your insurance company as soon as possible after identifying roof damage. Delay in reporting could lead to complications with your claim. Most insurers have specific timeframes within which claims must be filed after a storm event.
Schedule an Inspection
- Provide all documentation (photos/videos/notes).
- Be available during the inspection to answer questions about damages observed.
If possible, consider having a licensed roofing contractor present during this inspection to provide expert insights into necessary repairs or potential costs.
Get Repair Estimates
Although insurers may provide their own estimates through adjusters, obtaining independent quotes from reputable contractors ensures transparency and accuracy. These quotes can serve as leverage if there are discrepancies between what is offered by insurance and actual repair costs.
Task | Why It Matters |
Document Damage | Ensures comprehensive proof for your claim |
Notify Insurer Early | Avoid delays in compensation processing |
Obtain Estimates | Helps verify fair repair cost assessments |
Follow Up on Your Claim
- Keep track of all communications with your insurance company.
- Follow up periodically on the status of your claim if responses are delayed.
By staying organized and persistent during this stage, you can reduce unnecessary delays in receiving funds.
Avoid Common Mistakes
- Neglecting Documentation: Inadequate evidence weakens claims significantly.
- Delaying Notification: Late filings may result in denied compensation.
- Starting Full Repairs Before Approval: Always wait until the insurer approves repairs beyond temporary fixes unless safety is compromised.
Navigating an insurance claim after hurricane roof damage requires patience and careful attention to detail but doing so ensures you receive adequate support while minimizing out-of-pocket expenses. A thorough approach also positions you better should similar situations arise again in the future.