Make Sure You Have a Legitimate Claim
Before initiating any negotiations with your insurance company, it is critical to ensure that your roof replacement claim is valid and supported by evidence. Insurance companies are meticulous about verifying claims, and failing to meet their requirements could result in denial or reduced compensation. This section will guide you on how to determine whether you have a legitimate claim for roof replacement.
Understand What Your Policy Covers
The first step in verifying the legitimacy of your claim is to review your homeowner’s insurance policy. Common roof-related coverages include:
– Damage from natural disasters: Coverage for windstorms, hail, or falling trees may be included, but policies often exclude floods or earthquakes unless additional coverage was purchased.
– Sudden accidental damage: For instance, damage caused by fire or vandalism.
– Age of the roof: Some policies offer full replacement value only if the roof is under a certain age (e.g., 10–15 years). Older roofs may only qualify for depreciated value.
Check if there are exclusions in the policy language. For example, many insurers avoid paying for damage caused by wear and tear or lack of maintenance.
Document Roof Damage Thoroughly
To establish the legitimacy of your claim, gather comprehensive evidence of the damage sustained by your roof. This documentation will serve as proof when dealing with adjusters:
– Take clear photos and videos of damaged areas from multiple angles (include close-ups and wide shots). Consider documenting both interior (e.g., water stains) and exterior damage. – Keep records of maintenance performed on your roof prior to the incident. – Collect receipts for temporary repairs (like tarping) made to mitigate further damage.
Differentiate Between Normal Wear vs Covered Damage
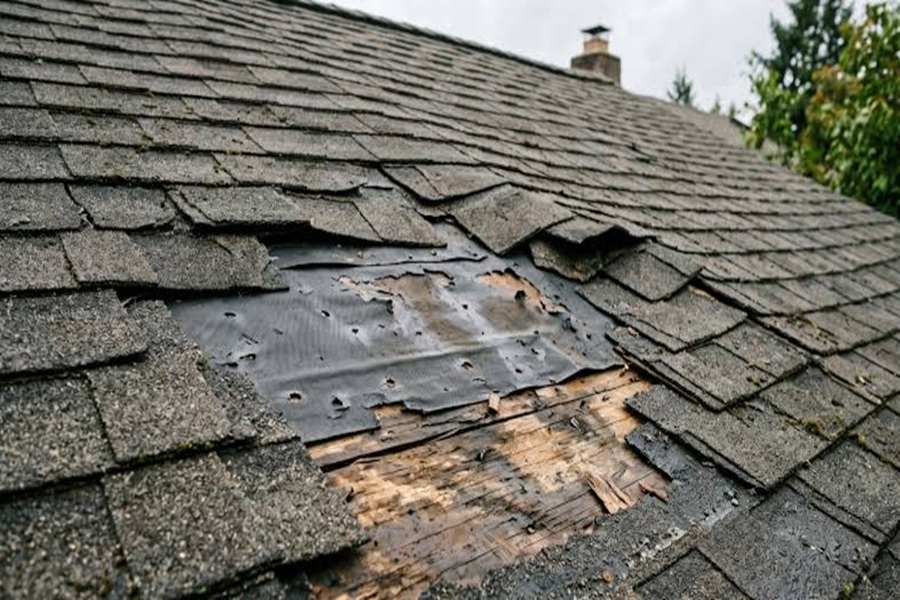
It’s essential to distinguish between natural aging and covered damages caused by sudden events. An insurance adjuster might argue that some issues—such as missing shingles—are due to wear rather than storm impact. If possible, consult with a professional roofing contractor who can provide an unbiased assessment of what caused the damage.
Type of Damage | Likely Covered? | Reason |
Hail causing shingle cracks | Yes | Hailstorms are typically covered events. |
Tree branch breaking roof tiles | Yes | Resulting from high winds or storms. |
Mold growth from old leaks | No | Considered ongoing neglect or lack of upkeep. |
Verify Timeliness Requirements
Most insurance policies have time limits on when claims can be filed after an event occurs. Missing these deadlines automatically invalidates otherwise legitimate claims. Check whether you’re still within the allowable timeframe outlined in your policy.
Consider Independent Inspections
If you’re unsure about whether you have valid grounds for filing a claim, hiring an independent inspector can help add credibility to your case before proceeding with negotiation efforts. A certified roofer or public adjuster can evaluate the extent of damage objectively while providing advice tailored specifically to your situation.
Taking these preparatory steps ensures that not only do you have a valid claim but also that you approach negotiations with confidence backed by evidence and expertise—a necessity when working with insurance companies aiming to minimize payouts at every opportunity.
Prepare to Negotiate With Your Insurance Company
Negotiating with an insurance company for a roof replacement requires preparation, strategy, and a clear understanding of your policy and rights. This section will guide you through the essential steps to ensure you are well-equipped before engaging in discussions with your insurer.
Understand Your Insurance Policy
- Coverage Details: Identify whether roof damages are covered under your policy. Some policies cover full replacement costs, while others only cover the depreciated value of the roof.
- Exclusions: Check for specific exclusions related to roof damage, such as neglect or pre-existing conditions.
- Deductibles: Know how much money you are responsible for before insurance coverage begins.
- Time Limits for Filing Claims: Ensure you’re aware of any deadlines for reporting damage or filing claims.
Having a strong grasp of your policy’s terms will prevent misunderstandings during negotiations and allow you to advocate effectively.
Document the Damage Thoroughly
- Take clear photos of visible damage from multiple angles.
- Include wide shots showing overall impact and close-ups capturing specific issues like missing shingles, cracks, or leaks.
- Video Footage: A video walkthrough can provide additional context that photographs might miss.
- Professional Inspection Reports: Hire a licensed roofing contractor or inspector to assess the damage and provide a detailed report outlining necessary repairs or replacement.
This evidence bolsters your case by providing objective proof that supports your claim.
Research Local Roofing Costs
- Obtain multiple quotes from reputable roofing contractors.
- Compare these estimates with any appraisal provided by the insurance adjuster.
- Create a list of material costs (e.g., shingles, underlayment) based on local suppliers.
Including this data in negotiations ensures you can make an informed argument if the insurer underestimates repair expenses.
Communicate Effectively With Adjusters
- Be polite but assertive during all conversations.
- Keep detailed records of every communication (e.g., phone calls, emails).
- Provide copies of all documentation – photos, inspection reports, contractor estimates – when meeting with adjusters.
You should also ask clarifying questions about how they reached their conclusions regarding coverage and costs.
Consider Hiring Public Adjusters
- Review policy details to ensure maximum coverage is applied correctly.
- Handle communications directly with the insurance company on your behalf.
- Negotiate fair settlement amounts based on independent findings.
While public adjusters charge fees (usually a percentage of the settlement), they can be invaluable if negotiating becomes overly complex or contentious.
Summary Table: Preparation Checklist
Task | Action Required |
Review Insurance Policy | Understand coverage/exclusions |
Document Damage | Take photos/videos; get inspections |
Research Local Costs | Obtain quotes from contractors |
Organize Evidence | Create files for all documents |
Consider Professional Help | Hire public adjusters if needed |
By preparing thoroughly using these steps, you’ll enter negotiations feeling confident and well-informed about what you deserve under your policy terms.
File a Rock Solid Insurance Claim
When dealing with roof replacement negotiations, the strength of your insurance claim plays a pivotal role in determining the outcome. Filing a thoroughly documented and well-prepared claim can significantly improve your chances of success. Below are key steps to ensure your claim is rock solid.
Document All Damage Thoroughly
Proper documentation is the foundation of a strong insurance claim. Take the following actions:
– Photograph Damage: Capture detailed images of all affected areas, including roofing materials, gutters, interior ceilings (if water damage occurred), and any other impacted structures.
– Videos for Clarity: Record videos of the damage to showcase its extent and provide additional context that photos might not capture.
– Time Stamps: Ensure photos and videos are time-stamped to show when the damage occurred or was discovered.
Review Your Insurance Policy
Understanding your policy is critical before you file a claim. Look into the following aspects:
– Covered Perils: Verify whether the cause of damage (e.g., hail, windstorm) is listed as a covered peril under your policy.
– Exclusions: Be aware of exclusions like wear-and-tear or pre-existing conditions that could lead to a denial.
– Deductibles: Know the deductible amount you’ll need to cover before your insurance kicks in for repairs or replacement.
Obtain an Inspection Report
Hiring an independent professional inspector can strengthen your case by providing an unbiased assessment of the damage. Here’s how it helps:
– A third-party inspection adds credibility to your claim by identifying issues that may not be apparent to untrained eyes. – It ensures no damage is overlooked, which is important when filing for comprehensive coverage.
Keep Records of Communication
Organization and transparency are vital throughout this process:
– Maintain a log for all interactions with contractors, insurance adjusters, and inspectors. – Include dates, times, names, and details discussed during phone calls or emails. – This could serve as evidence if disputes arise later. – Use written communication whenever possible for accuracy and reference.
Type of Communication | Examples | Importance |
Phone calls | Initial contact with insurer | Log details in case they’re needed later |
Email correspondence | Adjuster follow-ups | Written proof of interactions |
Inspection notes | Contractor/inspector insights | Helps back up claims with specifics |
Provide Detailed Estimates
Request quotes from roofing contractors who specialize in storm-related repairs or replacements. Insurers often require at least one estimate from licensed professionals before approving claims. Consider these steps:
1. Obtain multiple estimates to showcase consistency in repair costs.
2. Ensure each estimate includes detailed line items (e.g., shingles type, labor charges) for clarity.
By delivering comprehensive estimates alongside visual evidence (photos/videos) and inspection reports, you build a robust case that leaves less room for dispute.
Submit Your Claim Promptly
Timeliness is crucial when filing an insurance claim:
– Most policies include specific deadlines for reporting damage after an incident occurs. – Waiting too long could result in delays or outright rejection due to non-compliance with time-sensitive requirements.
Being proactive about gathering evidence and submitting paperwork ensures fewer delays during processing.
By approaching every aspect strategically—documentation, communication management, professional assessments—you create an airtight foundation upon which successful negotiations can be built during discussions with insurers about roof replacement coverage needs.
Key Negotiation Tips
When dealing with your insurance company about a roof replacement, effective negotiation can make a significant difference in the outcome. This process requires preparation, patience, and a strategic approach to ensure your claim is handled fairly. Below are actionable tips to help you navigate the negotiation process successfully.
1. Understand Your Policy Inside Out
- Review Coverage Details: Start by thoroughly reviewing your homeowner’s insurance policy. Look for specific information on roof damage coverage, exclusions, deductibles, and limits.
- Identify Covered Perils: Understand what types of damage (e.g., hail, windstorms) are explicitly covered and confirm that the cause of your roof issues falls within these parameters.
- Clarify Terminology: Policies often include complex legal terms. If you’re unclear about certain provisions, consult an insurance expert or attorney before proceeding.
2. Document Everything Thoroughly
Proper documentation is essential for strengthening your position when negotiating with the insurer. Make sure you have organized records that clearly demonstrate the extent of the damage.
- Photographs and Videos: Take clear photos or videos of the damaged areas from multiple angles before any repairs are made.
- Inspection Reports: Obtain an independent inspection report from a licensed roofing contractor to support your claim.
- Receipts and Estimates: Collect any relevant receipts for temporary repairs or prior maintenance work and secure detailed repair cost estimates from contractors.
3. Be Prepared to Advocate for Yourself
- Remain Calm but Firm: Always stay professional during discussions while defending your stance with confidence.
- Focus on Evidence: Use documentation such as contractor estimates or inspection reports to back up your arguments.
- Challenge Lowball Offers: If you receive an initial offer that seems unreasonably low, don’t hesitate to counter it with evidence-based figures.
4. Leverage Professional Help When Needed
Expert | Role in Negotiation |
Public Adjuster | Reviews claims independently and negotiates with insurers on your behalf. |
Roofing Contractor | Provides detailed assessments of damage and repair costs that support your claim. |
Attorney | Advises on legal rights if disputes escalate beyond negotiation. |
5. Be Patient But Persistent
- Follow up regularly without being overly aggressive.
- Keep track of all communication (emails, phone calls) for reference.
- Stay proactive by providing requested documentation promptly.
By adopting these strategies during negotiations, you’ll improve your chances of securing fair compensation for your roof replacement while maintaining professionalism throughout the process.
Key Negotiation Tips
When negotiating a roof replacement with your insurance company, preparation and strategy are vital. Insurance companies aim to minimize payouts, so approaching the negotiation with confidence and knowledge can help you secure the compensation you deserve. Below are actionable tips to guide you through the process effectively.
Understand Your Policy
Before entering negotiations, take time to review your homeowner’s insurance policy. Pay close attention to:
– Covered Perils: Identify whether damages caused by events like storms, hail, or windfall are included in your policy.
– Exclusions: Understand what is specifically excluded (e.g., normal wear and tear).
– Deductible Amount: Be aware of how much you’re responsible for paying before coverage applies.
If any part of the policy language is unclear, consult your agent or consider hiring a public adjuster for clarification.
Document All Evidence
Providing strong evidence strengthens your claim and can make negotiations more seamless. Ensure that all aspects of the damage are thoroughly documented:
1. Photographs: Take detailed photos of all visible damage from multiple angles, including interior leaks caused by roof issues.
2. Inspection Reports: Obtain a professional inspection from a licensed contractor or roofing expert to identify hidden damage not visible at first glance.
3. Estimates: Collect written estimates from contractors to show realistic repair or replacement costs.
Well-organized documentation makes it harder for an insurer to dispute the extent of damages.
Communicate Effectively
How you communicate with your insurance company matters significantly during negotiations: – Be polite but firm in all interactions with claims adjusters. – Ask questions if something seems unclear or inconsistent in their explanation. – Keep records of every conversation, including dates, names of representatives spoken to, and summaries of discussions.
Proactive communication shows that you are serious about reaching a fair resolution without unnecessary delays.
Leverage Professional Help
Sometimes hiring experts can improve your chances during negotiations: – Public Adjusters: These professionals work on behalf of policyholders (not insurers) to assess damages and negotiate claims. – Roofing Contractors: A trusted contractor’s detailed report can serve as critical evidence when challenging an adjuster’s findings. – Legal Advice: If the insurer denies the claim unfairly, consult an attorney experienced in insurance disputes.
While these services may require upfront fees or percentages from settlements, they often result in higher payouts overall.
Stay Persistent
Insurance companies may employ tactics like lowball offers or delays as part of their process. To avoid being discouraged: – Push back respectfully on low offers by providing your documentation as proof. – Follow up regularly if there are delays—don’t hesitate to escalate unresolved issues to management when needed.
Persistence signals that you’re committed to securing fair compensation without simply accepting initial decisions.
By combining preparation with strategic actions like maintaining clear communication and seeking professional assistance where necessary, you increase the likelihood of a favorable outcome during roof replacement negotiations with your insurer.
Key Negotiation Tips
When approaching negotiations with your insurance company regarding a roof replacement, preparation and strategy are key. Negotiating effectively can ensure that you get the compensation you deserve while maintaining a professional relationship with your insurer. Below are specific tips to help you navigate this process confidently.
1. Understand Your Policy Inside and Out
Before initiating any negotiation, it’s critical to review your insurance policy thoroughly. This understanding ensures that you’re aware of what is covered under your policy and prevents miscommunication or misinterpretation during the process.
- Coverage details (e.g., replacement cost vs. actual cash value).
- Exclusions or limitations related to roof damage.
- Deductible amounts.
- Filing deadlines for claims.
By being fully informed about your policy, you’ll be better equipped to counter any arguments from the insurer.
2. Document Everything Thoroughly
Proper documentation strengthens your claim and aids in negotiations by providing concrete evidence of the damage.
- Photos or videos showing the damage from multiple angles.
- Date-stamped images of the roof before the incident (if available).
- Contractor estimates outlining repair or replacement costs.
- Inspection reports from licensed professionals.
Having this information on hand allows you to substantiate your claim during discussions with adjusters or representatives.
3. Be Professional but Firm
Maintaining a respectful tone while standing firm on valid points is crucial in negotiations. Insurance companies often have policies and procedures they must follow, so patience is key.
- Use polite language even if disagreements arise.
- Avoid emotional arguments; rely on facts and documentation instead.
- Reiterate details from your policy when discussing coverage disputes.
Demonstrating professionalism builds trust but also conveys that you’re serious about achieving a fair resolution.
4. Get Multiple Estimates
Obtaining estimates from different roofing contractors can give you a clearer idea of reasonable costs for replacing your roof. It also serves as leverage in case the insurance company attempts to undervalue their settlement offer.
Item | Contractor A | Contractor B | Contractor C |
Total Replacement Cost | $12,000 | $13,500 | $11,800 |
Estimated Completion Time | 7 days | 6 days | 8 days |
Providing these comparisons can strengthen your argument by showing market-based pricing for labor and materials.
5. Be Prepared to Escalate If Necessary
- Request a re-inspection – This involves sending another insurance adjuster out for further evaluation of the damage.
- Engage an independent appraiser – Many policies include an appraisal clause allowing both parties to appoint neutral third parties for dispute resolution.
- Consider legal representation – In extreme cases where resolutions cannot be reached, consulting an attorney who specializes in insurance claims may be necessary.
These steps show that you’re serious about receiving fair compensation without rushing into legal action prematurely.
By following these strategies during negotiations, you’ll improve your chances of reaching an agreement that accurately reflects the scope of damages and associated repair costs without unnecessary delays or compromises on quality standards.
Key Negotiation Tips
When negotiating with your insurance company for a roof replacement, preparation and strategy play significant roles in securing the best outcome. Insurance companies are often focused on minimizing their payouts, so understanding how to approach negotiations can make a considerable difference. Below are key tips to help you navigate the process effectively.
1. Understand Your Policy Inside-Out
- Review Coverage Details: Thoroughly examine your homeowner’s insurance policy to understand what is covered and what isn’t. Look for specific clauses related to roof damage, replacement costs, exclusions, and deductibles.
- Know the Terminology: Familiarize yourself with terms like “replacement cost coverage” (which pays for a new roof) versus “actual cash value” (which factors in depreciation). This knowledge can prevent misunderstandings during negotiations.
2. Gather Strong Evidence
Documentation is crucial when negotiating with your insurer. Compiling evidence ensures that you validate your claim and eliminate opportunities for the insurance company to dispute it. – Photographs and Videos: Take clear pictures or videos of the damage from multiple angles. Include both close-up and wide shots. – Inspection Reports: If possible, get an independent roofing contractor or inspector to assess the damage. Their report can serve as unbiased evidence supporting your claim. – Weather Reports: In cases of storm-related damage, obtain weather records showing the conditions at the time of the incident (e.g., hailstorms or high winds).
3. Stay Professional but Assertive
When dealing with insurance adjusters or representatives: – Be Courteous: Maintain a polite tone throughout all interactions; hostility could work against you. – Ask Questions: If details about their assessment seem unclear or unfair, don’t hesitate to ask for clarification or justify why you disagree. – Stick To Facts: Avoid emotional arguments and focus on concrete evidence such as repair estimates, inspection reports, or your policy terms.
4. Get Multiple Estimates
Obtaining several repair or replacement estimates from licensed roofing contractors can strengthen your case by providing a realistic range of costs: | Contractor Name | Estimate Amount | Materials Included? | |———————–|—————–|———————-| | ABC Roofing Co. | $9,500 | Yes | | XYZ Contractors | $10,200 | Yes | | Reliable Roofers Inc. | $9,800 | Yes |
Providing this table to your insurer demonstrates that you’ve done due diligence and are presenting fair market rates for repairs.
5. Anticipate Lowball Offers
Insurance companies may initially offer less than what is needed to replace your roof fully: – If the offer seems inadequate, don’t accept it immediately. – Politely request an explanation for how they calculated their amount. – Use estimates and inspection reports as leverage when countering low offers.
6. Consider Hiring a Public Adjuster
If negotiations become particularly challenging: – A public adjuster works directly on behalf of homeowners (not insurers) and can advocate for fair compensation based on damages. – While they charge fees (typically a percentage of any settlement), their expertise could result in a more favorable outcome.
By remaining prepared, professional, and persistent throughout these discussions with your insurer, you significantly increase your chances of reaching an agreement that covers the full cost of replacing your roof without unnecessary compromise.