Inspecting for Roof Water Damage
Regular roof inspections are essential to catch early signs of water damage before they escalate into costly repairs. Proactively assessing your roof’s condition can prevent leaks, structural issues, and even mold growth. Below is a detailed guide to help you effectively inspect for roof water damage.
Why Regular Roof Inspections Matter
Periodic inspections help identify:
– Leaks and Cracks: Even small cracks or gaps in roofing materials can allow water infiltration.
– Water Stains: These often signal hidden leaks that could lead to extensive interior damage if neglected.
– Roofing Material Deterioration: Over time, shingles, tiles, or metal roofing may wear out due to exposure to harsh weather conditions.
By catching these issues early, you can address them promptly and conserve both time and money.
Exterior Inspection
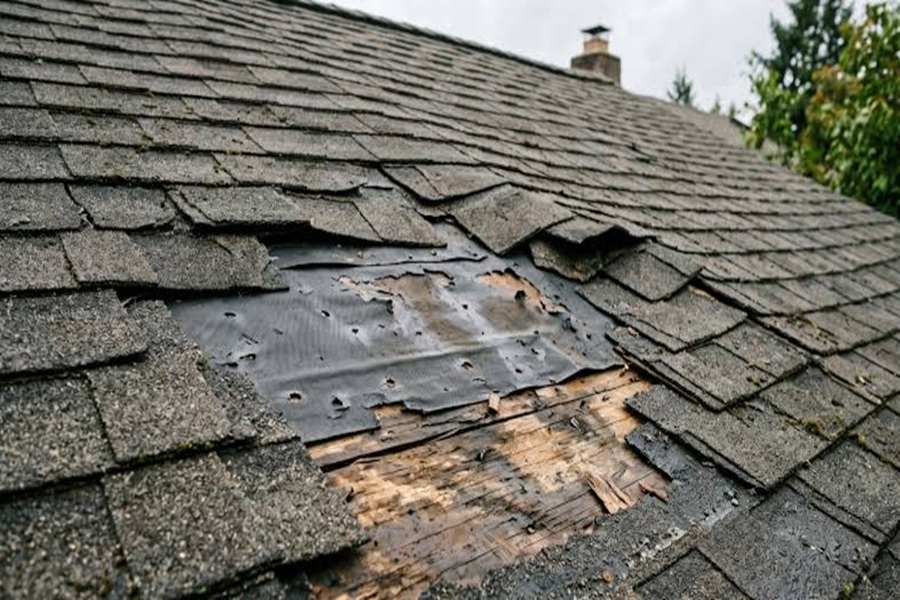
- Inspect for curled, cracked, or missing shingles that might allow water penetration.
- Pay attention to areas around vents, chimneys, and skylights where damage is more likely.
- Examine the flashing (metal strips that seal joints) for rust or detachment around chimneys and vents. Faulty flashing is a common entry point for water.
- Look for blockages caused by leaves or debris that could cause water overflow onto the roof.
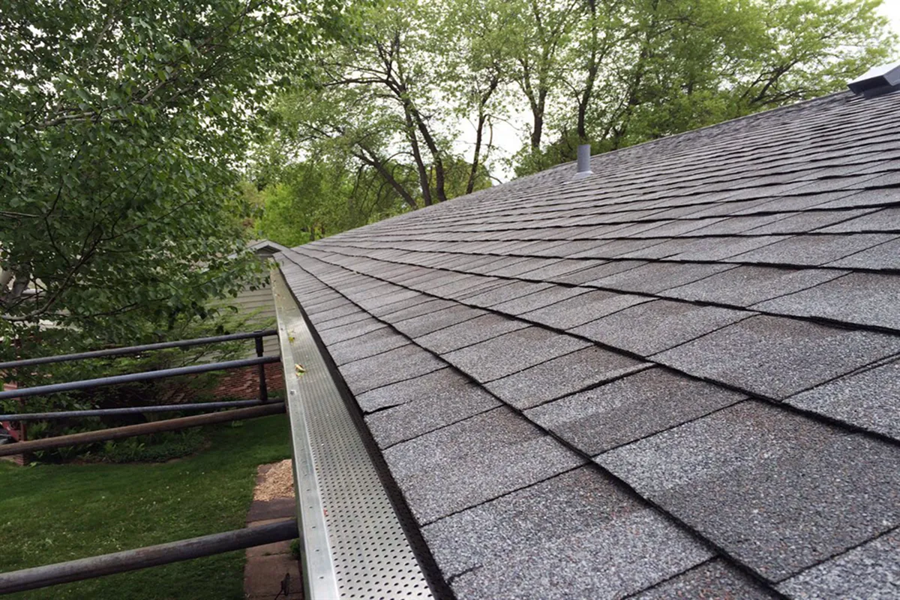
- Check if gutters are securely attached and functioning properly.
- Look for pooling water on flat roofs or depressions on sloped roofs where moisture can collect.
- Note any unusual discoloration that might indicate algae growth or moisture intrusion.
Interior Inspection
- Check ceilings for stains resembling coffee-colored rings—these are signs of leaks.
- Look at walls near corners or windows for peeling paint that could indicate excess moisture inside the structure.
- Use a flashlight to spot damp insulation, visible mold growth, or wet wood beams.
- During daylight hours, look for pinpricks of light coming through the ceiling—a clear sign of holes in your roofing material.
- Excess humidity in upper spaces might indicate poor roof ventilation—the trapped moisture can lead to long-term deterioration.
Tools You May Need
Tool | Purpose |
Flashlight | For inspecting attic spaces |
Binoculars | To examine hard-to-reach roof areas |
Ladder | For gaining access to rooftops |
Moisture Meter | To detect damp spots within walls |
Always prioritize safety when inspecting your roof; hire a professional if dealing with steep angles or elevated surfaces feels unsafe.
Signs You Should Call an Expert
- Persistent leaks despite repairs.
- Widespread shingle loss post-storm.
- Visible sagging sections on your roofline.
- Mold infestations requiring specialized treatment.
Professional inspectors use advanced techniques like infrared scanning to detect hidden water issues invisible during routine checks.
By understanding how and when to inspect your roof properly, you’ll safeguard it against the long-term effects of water damage while maintaining its structural integrity over time.
The Truth About Insurance
One of the most critical aspects of managing roof water damage effectively is understanding your insurance coverage. Many homeowners believe their home insurance policy will automatically cover all forms of roof damage, but this is not always the case. Insurance policies contain specific language, exclusions, and conditions that you need to be familiar with to avoid surprises in the event of roof leaks or weather-related damage.
Understanding Common Coverage for Roof Damage
Insurance policies generally fall into two categories when it comes to roof protection:
– Damage from Covered Perils: Most standard homeowner insurance policies cover “perils” such as windstorms, hail, fire, and heavy snow. However, neglect or lack of maintenance (like failing to repair a small leak) may void coverage.
– Exclusions for Wear and Tear: Damage caused by gradual wear and tear or improper installation is typically excluded from most policies. For example, if your shingles degrade over time due to age or poor ventilation in your attic, your claim may not be approved.
Key Questions to Ask Your Insurer
To ensure you’re prepared for potential water damage scenarios, ask these questions when reviewing your policy:
1. Does my policy cover roof leaks caused by storms?
2. Are there specific exclusions related to water infiltration?
3. Will my settlement be based on the replacement cost or actual cash value (ACV) of my roof? Replacement cost covers what it takes to fully repair or replace the damaged area without factoring in depreciation; ACV considers depreciation and provides less reimbursement as roofs age.
4. Are there separate deductibles for wind/hail damage? In some high-risk areas, insurers apply higher deductibles for these perils compared to general damages.
Claims Process for Roof Water Damage
- Document Evidence: Take photos and videos of the damaged areas as soon as it’s safe to do so. Ensure you capture both interior signs (e.g., water stains on ceilings) and exterior issues (e.g., missing shingles).
- Prevent Further Damage: Most insurers require homeowners to take steps—like placing tarps over exposed areas—to prevent additional harm while waiting for repairs.
- Contact Your Insurer Promptly: Notify your insurance company about the incident as soon as possible and follow their instructions regarding filing a claim.
- Get an Inspection: Many insurers will send an adjuster to assess the scope of the damage before approving repairs.
- Hire Reputable Contractors: When arranging repairs after approval, work with licensed contractors who have experience handling insurance claims.
Steps in Claims Process | Key Actions |
Document Evidence | Take photos/videos; record dates & details |
Prevent Further Damage | Cover exposed areas; mitigate risks |
Notify Your Insurer | Call quickly; provide detailed description |
Adjuster Inspection | Be present if possible during assessment |
Hire Reputable Contractors | Prioritize licensed professionals |
Proactive Steps with Insurance Policies
To avoid costly mistakes related to water-damaged roofs:
– Review your policy annually to stay informed about changes in coverage terms. – Consider adding supplemental coverage for perils like floods or hurricanes if applicable in your region. – Keep maintenance up-to-date—clean gutters regularly, inspect flashing after storms, and repair minor issues promptly.
A solid understanding of how insurance works can help save thousands of dollars during emergencies while giving peace of mind that you’re adequately protected against unexpected disasters affecting your roof systems.
Why Regular Inspections Are Important
- Prevent Escalating Costs: Addressing minor issues early can save thousands of dollars in repairs down the line.
- Extend Your Roof’s Lifespan: Routine checks can help maintain the longevity of your roofing materials by addressing wear and tear promptly.
- Protect Against Structural Damage: Undetected water damage can compromise beams, ceilings, and walls over time, leading to extensive repairs across multiple parts of the home.
Key Areas to Inspect
- Shingles: Look for missing, cracked, or curling shingles that could allow water to seep beneath them.
- Flashing: Check around chimneys, vents, skylights, and other protrusions where flashing protects seams from water entry. Corroded or loose flashing is a common source of leaks.
- Gutters and Downspouts: Ensure gutters are clear of debris and properly directing water away from your home. Blockages here can lead to pooling water on the roof.
- Attic Spaces: From inside your attic, inspect for dark spots, mold growth, or areas where light shines through—these may signal active leaks.
- Valleys and Low Slopes: Water tends to collect in valleys or low-sloped parts of a roof, making them more vulnerable to damage.
Tips for Effective Roof Inspections
- Use binoculars to examine hard-to-reach areas from the ground rather than attempting risky climbs onto the roof surface.
- Schedule inspections seasonally or after severe weather events like storms or heavy snowfall.
- Document any signs of potential problems through photos so you can monitor changes over time.
Professional vs DIY Inspections
Aspect | DIY Inspection | Professional Inspection |
Cost | Low (or no cost) | Moderate fee |
Risk | Potentially unsafe if climbing involved | Minimal risk |
Thoroughness | Limited by personal expertise | Highly detailed with expert tools |
Frequency Recommended | More frequent | Yearly or after major weather events |
Acting on Inspection Findings
If you notice any signs of trouble during an inspection—such as damaged shingles or leaks—address them promptly through repairs or maintenance work.
By staying vigilant about inspecting your roof regularly and being proactive when issues arise, you’ll create an effective first line of defense against water damage caused by leaks and inclement weather conditions. This habit not only protects your investment but also ensures peace of mind during rainy seasons or extreme weather events.
What Does Homeowners Insurance Typically Cover?
- Sudden and Accidental Damage: If your roof is damaged suddenly by a covered peril such as a storm, hail, or falling debris (like tree branches), repairs are often covered.
- Water Damage from Storms: Rainwater entering the house due to storm-created openings in your roof may also fall under coverage.
- Leaks Resulting from Covered Events: If a hole forms in your roof because of wind or hail during a storm, resulting leaks are commonly included in claims.
However, not all situations qualify under every policy. Insurance companies have exclusions and conditions that might affect whether or not they pay out for specific types of damages.
Common Exclusions You Should Know
While some scenarios are covered, others are frequently excluded from homeowners insurance policies:
– Wear and Tear: Normal aging or lack of maintenance on roofs is usually not covered by insurance. For example:
– Roof shingles reaching the end of their lifespan
– Gradual leaks caused by neglecting inspections/repairs over time
– Pre-existing Issues: Damages existing before obtaining your policy will likely be excluded from coverage.
– Flood Damage: Most standard homeowners policies do not cover flood-related issues unless you have additional flood-specific insurance.
Understanding these exclusions can help you avoid surprises when filing an insurance claim.
How Can You Maximize Coverage Under Your Policy?
- Document Regular Maintenance: Keep records of scheduled inspections and any professional repairs done on your roof to demonstrate that you’ve taken proper care of it over time.
- Act Quickly: Report potential damage immediately after storms or severe weather conditions; delays in reporting may lead insurers to deny claims.
- Know Your Deductible: Familiarize yourself with the deductible portion you’ll need to pay before claiming benefits—this ensures financial preparedness.
- Photograph Everything: Take clear photos documenting the condition of your home post-damage as evidence for claim validation purposes.
- Understand Policy Riders: If you live in regions prone to specific risks (e.g., hurricanes), consider adding additional riders like windstorm or hail protection.
Working with Adjusters
Insurance adjusters assess roofing damages during claim investigations—here’s how you can work effectively with them: – Provide all requested documents and photographs promptly. – Be present during inspections if possible; this ensures accurate evaluation. – Consider hiring an independent contractor for a second opinion if there’s a dispute about damages or repair costs.
Table – Quick Comparison Between Covered & Non-Covered Situations
Situation | Likely Covered? | Notes |
Storm-caused hole leading to leaks | Yes | Coverage depends on storm-related opening |
Gradual wear-and-tear leaks | No | Consider regular maintenance as prevention |
Damage due to poor installation | No | Faulty workmanship is typically excluded |
Hail damage | Yes | Most policies include hail-related events |
By understanding these elements about insurance coverage for roof water damage, homeowners can better navigate potential complications while ensuring they’re adequately protected financially against unexpected disasters such as severe weather conditions affecting their roofs directly.
Types of Coverage for Roof Water Damage
- Sudden and Accidental Damage: Most policies cover unforeseen events such as a tree branch falling on your roof during a storm, causing leaks and subsequent water damage inside the home.
- Wear and Tear or Neglect: Damage resulting from poor maintenance or gradual deterioration is rarely covered. For example, if your roof has aged shingles that weren’t replaced and they cause leaks, this would likely be excluded from coverage.
- Weather-Related Damage: Policies may cover damage caused by natural events like hailstorms, heavy winds, or snow buildup that leads to leaks. However, there may be exclusions depending on your location (e.g., hurricane-prone areas might require additional riders).
Key Considerations When Reviewing Your Policy
- Deductibles: Understand how much you’ll need to pay out-of-pocket before your insurance kicks in—higher deductibles could mean lower premiums but may also leave you with significant expenses during repairs.
- Exclusions: Look for any specific exclusions related to roofing materials (like flat roofs) or conditions (such as pre-existing issues).
- Replacement Cost vs. Actual Cash Value (ACV): Some policies only reimburse the depreciated value of your damaged roof rather than covering full replacement costs unless an upgrade has been purchased.
Coverage Feature | What It Means | Applicable Scenarios |
Deductible | Amount paid before coverage applies | Storm damage repair costs |
Exclusion | Items/policies NOT covered | Gradual wear & tear from old shingles |
Replacement Cost | Full replacement value reimbursed | Hail-damaged newer roofs |
Actual Cash Value | Depreciated reimbursement value | Aging roofs without upgrades |
Tips for Filing a Claim Effectively
- Document the damages immediately with photos or videos after discovering leaks or structural problems.
- Contact your insurance provider promptly—most policies require reporting within a specific timeframe.
- Keep receipts for temporary repairs made to prevent further water damage while awaiting professional repairs.
- Obtain estimates from licensed roofing contractors as evidence when negotiating claims.
Additional Riders and Specialized Policies
- In flood-prone zones, consider purchasing separate flood insurance since standard homeowner’s policies exclude flood-related damages.
- Earthquake-prone areas may require additional endorsements covering structural risks during such events.
By better understanding your policy’s scope—alongside proper documentation + proactive inspection/hiring licensed pros-youre empowered better outcome fewer disputes handling future concerns
What Does Homeowners Insurance Typically Cover?
- Covered Events:
Insurance usually covers sudden and accidental damage caused by events like: - Storms (e.g., hail, wind, heavy rain)
- Falling objects (e.g., trees or debris)
- Fire
- Excluded Causes:
Damage caused by the following is typically not covered: - Gradual wear and tear or lack of maintenance
- Pre-existing conditions before the policy started
- Flooding or water backup from clogged drains (often requires separate flood insurance)
Understanding these distinctions can help you avoid financial surprises when filing a claim.
How to Strengthen Your Coverage
- Document the State of Your Roof: Regularly take photos of your roof and keep records of inspections or repairs. In the event of a claim, this documentation can be critical in proving that your roof was well-maintained before an incident occurred.
- Add Endorsements if Necessary: If you live in an area prone to flooding, hurricanes, or other extreme weather conditions, consider adding riders or endorsements for better protection. For example:
| Rider/Endorsement Type | Covers | Cost Consideration |
|————————|——–|———————|
| Flood Insurance | Water damage from external flooding sources like rivers or storms | Varies by location & risk level |
| Roof Replacement Endorsement| Full replacement cost rather than depreciated value for older roofs| Slightly increases premium | - Review Your Policy Regularly: Policies vary significantly between providers and over time as insurers update their offerings. Take time annually to review coverage with your agent.
Filing an Insurance Claim for Roof Damage
- Contact Your Insurer Immediately – Notify them as soon as possible about potential claims while providing details such photographs documenting affected areas alongside written explanation why.
Common Types of Coverage for Roof Water Damage
- Storm Damage: Most standard homeowner policies will cover damage caused by sudden or accidental events like hurricanes, heavy rain, hailstorms, or wind.
- Gradual Leaks: Gradual leaks due to wear-and-tear are typically not covered. Homeowners are responsible for maintenance to prevent these issues.
- Flooding Exclusions: Standard policies often exclude flooding unless you have additional flood insurance coverage.
- Mold Damage: If mold results from unresolved water damage or neglect over time, insurers may deny coverage unless preventive measures were taken proactively.
Understanding Policy Limitations
- Age of Roof: Some policies reduce or eliminate coverage for roofs that exceed a specific age (e.g., 20 years).
- Coverage Caps: Policies may impose limits on what they pay for roof repairs or replacement.
- Deductibles: High deductibles often apply to roof-related claims—especially in disaster-prone areas where policies require windstorm or hurricane deductibles as a separate expense.
Carefully review these clauses in your policy documents so you’re not caught off guard if a claim is needed.
Steps To Take When Filing a Claim
- Document the Damage: Photograph affected areas as soon as it’s safe to do so.
- Mitigate Further Damage: Take immediate action (such as using tarps) to prevent worsening conditions while waiting on professional repair services.
- Notify Your Insurer Promptly: File your claim as soon as possible in accordance with your insurer’s deadlines.
- Keep Records of Expenses: Retain receipts for temporary fixes and alternative accommodations (if needed), as these may be reimbursable.
Action | Why It’s Important |
Document the damage | Provides evidence required during claim |
Notify promptly | Prevents delays due to missed deadlines |
Mitigate further risk | Helps avoid additional costs being denied |
Proactive Insurance Planning
- Schedule annual reviews with an insurance agent to confirm adequate coverage levels for your home’s location and condition.
- Invest in preventative maintenance like gutter cleaning and regular inspections (most insurers expect homeowners to take reasonable care of their property).
- Consider optional riders or endorsements that bridge gaps in standard policies—for example, adding flood or storm-specific protections if you live in high-risk regions.
Understanding the truths about insurance empowers you to make informed decisions about protecting one of your most important investments—your home—and ensures peace of mind when adverse weather strikes unexpectedly.